

Dear Investor,
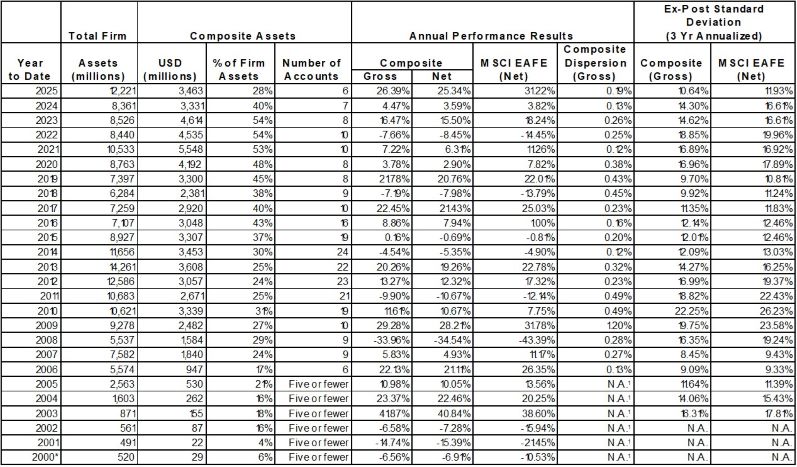
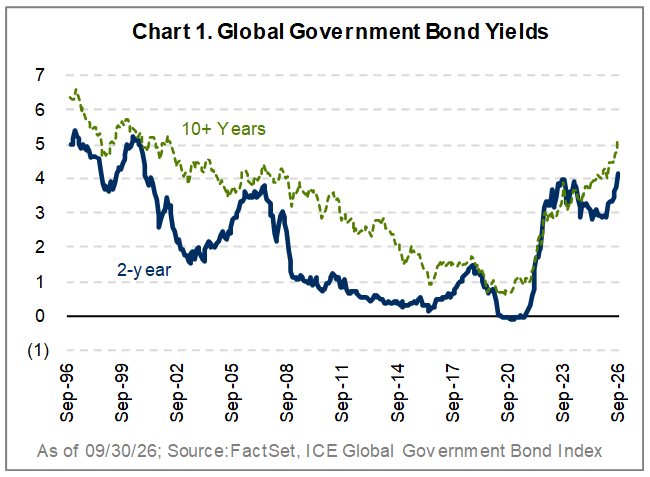
It was an eventful quarter as global bond yields rose sharply (Chart 1), renewed hostilities between the US and Iran set off another energy shock, and AI-related stocks swung widely. The Altrinsic International Equity portfolio gained 1.7% gross of fees (+1.5% net) in the third quarter, outperforming the 0.8% return of the MSCI EAFE Index, as measured in US dollars.i Our outperformance mainly stemmed from industrial businesses in Europe and Japan and a broadening of market leadership favoring the “quality” characteristics well represented in the portfolio.
The global macro environment is becoming increasingly fragile, with high debt levels and global growth that largely rests on three things: continued explosive AI capital spending, the ability of a handful of companies to finance it, and the wealth effect created by rising AI-related share prices. We continue to see the best opportunities among companies that may lack the aspirational narratives of today’s market darlings but offer more durable, achievable growth at attractive valuations.
Perspectives
The global macro environment is murky at best, but that fragility is creating attractive opportunities in less crowded areas of the market.
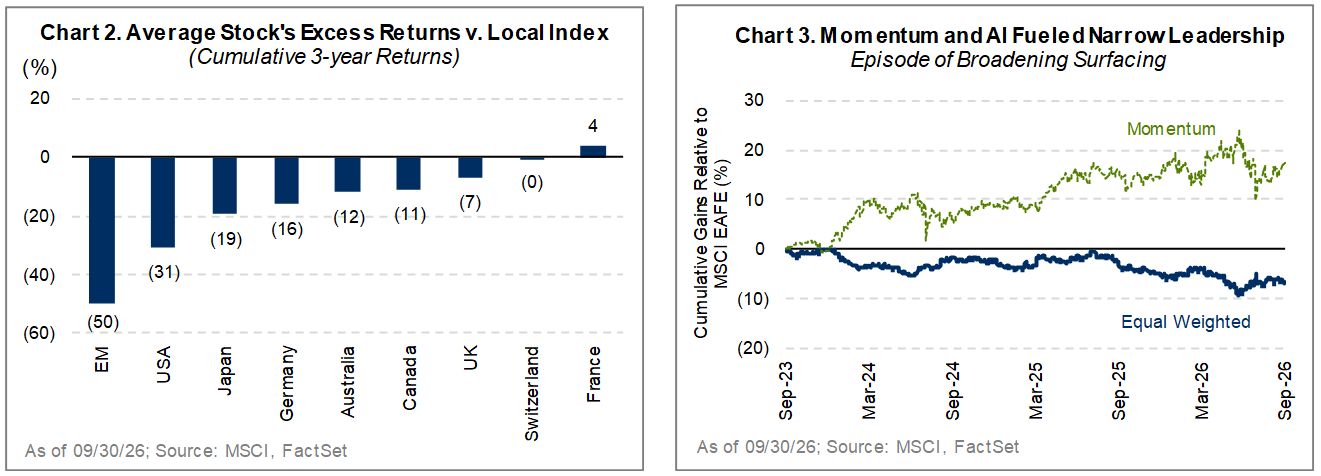
High government debt, fiscal deficits, rising interest rates, important elections (Brazil, Israel, US midterms, France, Italy, and Spain, among others), ongoing conflict in geopolitical hot spots (Ukraine, Iran), and a growing economic dependence on AI have created an unstable macro backdrop. Yet, markets have plowed right through. On closer inspection, only a small number of AI stocks have powered global index returns for years, while the average stock across most regions has lagged (Chart 2). International markets saw a brief rally in highly cyclical stocks last year, but the overall dynamic has been the same. Momentum has dominated markets since 2022; the equal-weighted index has underperformed the increasingly concentrated market-cap-weighted index (Chart 3). Only recently have we seen indications of broadening away from these trends. This is significant considering the valuations and compelling opportunities outside the narrow group that has led markets in recent years.
A key development during the quarter was the extent to which stock markets shrugged off rising interest rates and tightening financial conditions in many large countries.
It takes time for rising rates to work their way through economies and markets, but markets tend to respond before economies do. The pace, scale, and underlying reasons for rising rates play a key role. Every situation is different, but negative developments often occur when interest rates rise above 5% in developed markets and above 8% or 9% in emerging markets. Many fundamental and macro factors influence market sensitivity to interest rates, including market composition, leverage, duration, valuation, and growth. Among these, “growth” expectations associated with AI have been dominant.
Excitement behind the AI narrative and the expectation that AI-driven growth will remain resilient amid tighter financial conditions has underpinned much of the strength in market cap-weighed indices.
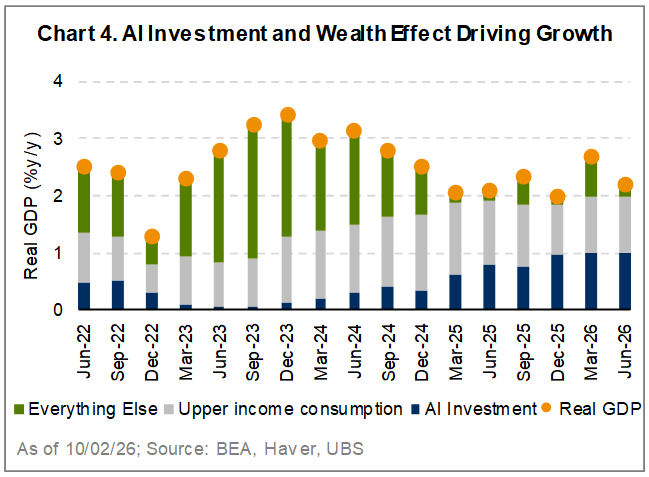
AI feeds the economy through both data center capex and the wealth effect from rising AI equities. UBS estimates these factors have driven most of the United States’ growth over the past year, with relatively little contribution from the rest of the economy (Chart 4). Because much of the hardware for AI infrastructure is imported, the investment boom also generates significant global spillovers. Goldman Sachs estimates that AI-related spending will contribute between 40% and 90% of economic growth in 2026 for many Asian countries, including 80% for Taiwan and 90% for South Korea.1
These wide-ranging effects make the durability of AI investment a critical consideration.
Data centers earn strong returns because computing capacity is scarce. The question is whether those returns hold as supply catches up, financing needs grow, and the cost of capital rises. Three risks stand out: circularity, debt, returns.
Circularity: OpenAI and Anthropic have committed to spend more than $1 trillion, most of it funded from external sources, on computing capacity. That amount is close to half of the contracted future business of the four largest US cloud providers, and most of it will not start generating revenue until 2027-2028. Newer data center companies, often called “neoclouds,” are borrowing against these contracts, and suppliers such as NVIDIA have begun guaranteeing some of those loans. In effect, “anticipated” AI revenue is financing today’s build-out. This loop fuels the boom for now but would magnify the damage if OpenAI/Anthropic revenues disappoint, demand falls short, or borrowing becomes more expensive.
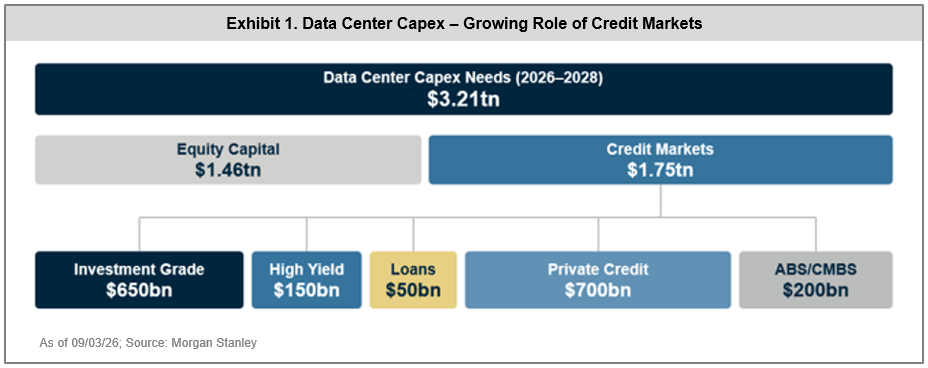
Debt: The hyperscalers are increasingly borrowing to fund AI, both on and off their balance sheets. Capex is expected to absorb close to 100% of their operating cash flow by the end of 2026, versus about 40% in 2023.2 Furthermore, two-thirds of build-out spending goes to servers and chips that are depreciated over five to six years, yet the hardware may be obsolete before the debt is repaid. Growing uncertainty has begun to be priced into credit and derivative markets, as evidenced by Oracle’s five-year CDS widening to about 240 bps (up from 144 bps at the start of 2026) and bonds by neoclouds like CoreWeave now yielding well into the double-digits. As shown in Exhibit 1, credit markets are expected to fund more than half of the roughly $3.2 trillion of data center spending projected for 2026-2028. The issue for the AI food-chain is that the funding of capex is increasingly reliant on the “kindness of strangers,” and if borrowing costs rise sharply or equity market optimism wanes, the ability to fund would worsen considerably.
Returns: Strong demand does not guarantee strong returns. While the internet’s winners had years to build scale in their own markets before rivals arrived, today’s hyperscalers and labs are competing head-on before the returns are proven. Amazon’s AWS faced little serious competition for nearly a decade. By comparison, open-source AI models that anyone can download only trail the leading models by about four months. The risk is that more robust competition could push returns below a rising cost of capital, essentially neutralizing the power of demand.
Pressures are already visible in credit markets. AI-related debt issuance is expected to exceed $500B in US markets this year.3 That supply competes with Treasuries for the same investors, and with the 10-year yield above 5%, the cost of capital has risen for every borrower. Stronger borrowers can absorb this shift; weaker ones are feeling the strain. We continue to believe AI will be an incredibly productive technology, but the issues listed above highlight that exponential growth is not a guarantee, and the path may be rockier than many anticipate.
Headlines about Europe focus on challenging macro conditions, but economies are not markets, and we see compelling investment opportunities.
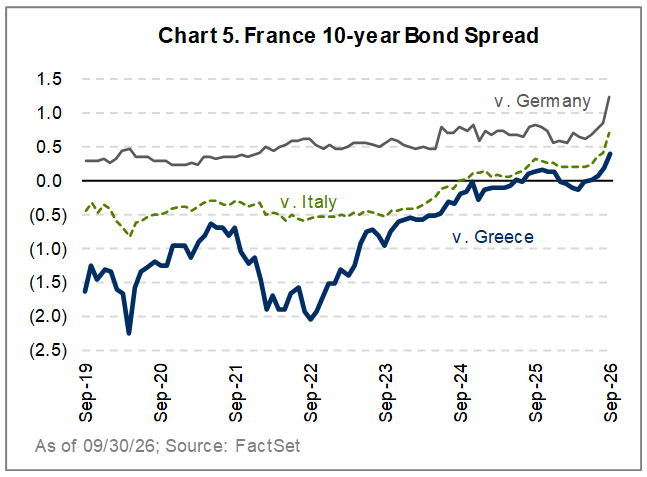
Europe faces high debt levels, fiscal pressure, lagging productivity, societal issues around a busy election cycle, and energy strains entering the winter season. Fiscal strains in France have pushed this “core” EU nation’s 10-year borrowing costs above those of once-ridiculed Greece and Spain (Chart 5). Structural macro reforms have been slow, but micro change at the company level has been meaningful, reflected in improving margins, financial productivity, and capital efficiency. Growing shareholder activism and private equity activity are accelerating that change.
Our European investments have performed well, delivering solid results thus far in 2026, with average EPS growth of 15%. We continue to have meaningful EU exposure and a compelling pipeline of new investments. Recent purchases include Swedish industrial software maker Octave, leading food services outsourcer Compass Group, aircraft maker Airbus, German aircraft engine and services company MTU Aero Engines, and pharmaceutical leader AstraZeneca.
Japan appears to have escaped the deflation that has plagued it for decades, market reforms are underway, and more companies are focusing on shareholder value.
However, Japan faces similar macro challenges to those in Europe, with an even more difficult demographic profile. The sharp jump in bond yields creates headwinds, but Japanese households stand to benefit as their enormous cash savings finally begin earning a return. As we have noted in recent commentaries, Japanese interest rates and yen movements have global implications. The yen has been a low-cost funding currency, Japan owns a vast amount of foreign assets, and changes in either can affect global liquidity and the pricing of risky assets. This warrants close monitoring.
The blend of macro uncertainty and company-specific change that we have identified in Europe also defines Japan. Our Japanese investments have evolved from being heavily concentrated in financial companies to spanning consumer, industrial, technology, and real estate businesses. Sony is one of our large positions. The company has steadily shifted its business away from more volatile drivers like consumer electronics and insurance, instead focusing on products that provide greater pricing power and differentiation and produce strong recurring cash flows. Some examples include gaming, music, and image sensor technology. In the short term, the business is seeing profit pressure from rising memory costs, but we believe Sony’s transformation has produced a far more resilient business than many investors realize. While we did not make any new Japanese purchases during the quarter, we view Japan as a fertile source of investment opportunity.
Emerging markets offer a similarly mixed picture, with compelling and growing opportunities beyond the major market constituents.
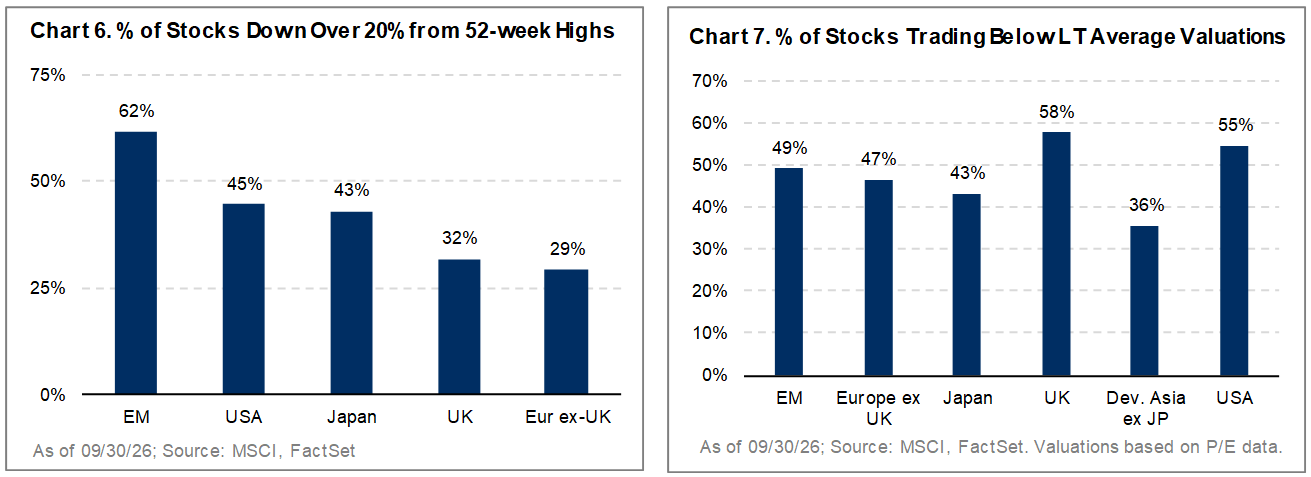
Rising global interest rates and the prevailing energy shock have weighed on many emerging market economies, particularly energy importers with external imbalances (India, Philippines, Thailand, Indonesia). As shown in Chart 6, 62% of EM stocks are more than 20% off highs, and valuation measures are below long-term averages (Chart 7).
A narrow view of emerging markets, as defined by the highly concentrated EM index dominated by a handful of companies, offers a misleading picture of the opportunity set compared to a bottom-up, company-specific approach. The technology sector, now representing 44% of the index, has surpassed China’s 2020 peak weight, and Taiwan and South Korea together now exceed 50%.4 These are the same AI-linked areas where expectations are highest, leaving the index more exposed to the AI-related risks discussed earlier. Looking across EM, we see the greatest opportunities in Latin America, Southeast Asia, and India, with growing interest in China.
Closing Thoughts
Global market performance, driven by a highly concentrated set of leaders, has defied rising bond yields, tighter financial conditions, and an increasingly fragile macro backdrop. However, we believe that resilience rests on a precarious foundation of heavy AI spending, funding that increasingly relies on outside capital, and a wealth effect linked to rising equity market valuations. Together, these leave little margin for disappointment. Even as the index remained narrow, leadership began to broaden toward the quality characteristics well represented in our portfolio, and our holdings in Europe and Japan continued to demonstrate that economies are not markets.
The greatest risks often come from the unknown. At present, the most visible ones stem from a material disappointment in the AI “narrative,” rising rates, and deteriorating geopolitics. Looking ahead, we see the best opportunities where macro headlines may appear challenging but company-level opportunities are most compelling. We expect Europe, Japan, and emerging markets to be enduring sources of opportunity.
We will be disciplined and opportunistic, guided by the same principles that have anchored us since our founding in 2000: quality of business, price paid, and margin of safety. We believe this is a time when being different from the market may be rewarded, provided it is done prudently and with those principles at the forefront. As always, we thank you for your continued partnership and trust.
Sincerely,
John Hock
John DeVita
Rich McCormick
Appendix: Q3 Performance Attribution and Investment Activity
A broadening of market leadership beyond companies tied to AI infrastructure supported the portfolio’s relative performance. The greatest sources of positive attribution came from our investments in Europe (ex-UK) and among the industrials, technology, and consumer discretionary sectors. The largest performance detractors were in the consumer staples and materials sectors.
Among our industrials investments, Kingspan was a notable contributor to performance. The Ireland-based company, led by the founder’s ambitious son Gene Murtagh, saw growth accelerate across its value-added construction materials businesses. Its announced acquisition of power systems producer BMC Manufacturing should expand Kingspan’s presence in data center construction and advance its broader strategy of leveraging high-performance products to gain share in adjacent markets.
Our underweight exposure to semiconductor suppliers was a small source of positive attribution, as the sector fell 8.6% in the quarter. Concerns about power availability, regulatory hurdles for new projects, and price competition from China raised questions about the sustainability of unusually high profits for these companies. We see better value in businesses with the potential to use AI to improve efficiency, particularly where valuations do not reflect the possible gains.
Sony led performance among our consumer discretionary investments. Shares rose as profitability proved resilient despite higher component costs, and its opportunities in AI gained greater recognition. Sony’s platforms stand to benefit as AI expands content availability, while its leadership in image sensors and sensing technology provides a strong footing to serve growing demand for AI applications in the physical world.
Negative attribution came primarily from consumer staples. The sector continues to lag markets despite deeply discounted valuations, as investors remain disappointed about lackluster household consumption. In particular, our investment in Danone sank following a brief infant formula recall, heightened competition in yogurt, and rumors of a large acquisition that was subsequently denied. We believe these issues are temporary, and Danone’s focus on health and nutrition should benefit from underlying consumption trends.
CRH weighed on the portfolio’s materials performance, as higher commodity prices favored basic commodity producers and raised concerns about input cost inflation for building materials companies. We view CRH’s vertically integrated business model as a competitive advantage that positions it to gain market share and benefit from sustained highway and road infrastructure investment.
During the quarter, we initiated positions in four companies (AstraZeneca, Samsung Fire & Marine, Compass Group, MTU Aero Engines) and exited eight holdings (Daimler Trucks, Hana Financial, Zurich Insurance, KB Financial, Techtronic, DHL, Capgemini, Hexagon).
We are finding compelling value in companies that have made significant strides to improve their overall business quality and have credible opportunities to improve returns over the next several years. AstraZeneca has transformed itself into a global pharmaceutical leader through successful diversification and substantial pipeline investment. The company now has one of the industry’s deepest and most advanced drug pipelines, which coupled with its strong R&D track record, should underpin earnings expansion to offset patent expiries over the next decade. Similarly, Samsung Fire & Marine has improved its business mix and balance sheet to become one of the most competitive non-life insurance companies in South Korea. We see an attractive path forward for the company under new, shareholder-friendly leadership and a more supportive competitive backdrop while smaller peers seek to improve weak profitability. Compass Group has established a formidable position in the fragmented contract caterer industry, and its operating leverage improves with greater purchasing scale and supply chain utilization. The company has an impressive management team and continues to gain share in the growing market for outsourced food services. Lastly, MTU is transitioning from a period of heavy investment in new aircraft engines to decades-long aftermarket earnings as its installed base expands to address structural aerospace undersupply.
We divested our holdings in Daimler Trucks, Hana Financial, Zurich Insurance, KB Financial, Techtronic, DHL, Capgemini, and Hexagon as share prices reached our estimates of intrinsic value and better opportunities presented elsewhere.